The financial markets opened Monday under heavy pressure as a fresh wave of geopolitical tension triggered a sharp oil price surge, sending Wall Street into reverse and reigniting concerns about inflation, energy security, and the broader health of the global economy. With U.S. forces conducting targeted strikes against Iranian military positions along the critical Strait of Hormuz, investors braced for what could be a prolonged period of market volatility heading into the final months of the year.
This latest escalation marks the first major military action in roughly a month, breaking a relative pause in hostilities that had previously given markets brief windows of optimism. Now, with energy infrastructure under threat and a crucial maritime chokepoint potentially in jeopardy, traders are once again pricing in substantial risk across multiple asset classes.
Stocks Slide Across the Board as Energy Sector Defies the Trend
The benchmark S&P 500 opened lower, shedding roughly 0.4% in early trading, while the Dow Jones Industrial Average dropped 348 points, translating to a 0.7% decline. The tech-heavy Nasdaq followed suit, slipping 0.3% as the morning session progressed.
What made Monday’s pullback particularly striking was its breadth. Nearly every sector within the S&P 500 lost value, a sign that investor anxiety had moved well past simple risk recalibration and into something deeper. Yet, in a counterintuitive twist, energy stocks emerged as the day’s winners as the oil price surge lifted profit expectations across the petroleum sector. Exxon Mobil climbed 2.9%, while Chevron posted an even more impressive 3% gain, rewarding investors who had positioned themselves for exactly this kind of geopolitical premium.
Overseas Markets Send Mixed Signals
While American equities bore the brunt of the selloff, markets across Europe and Asia traded without a clear direction. European indices wavered between modest gains and losses as investors weighed the implications of higher energy imports, particularly for nations heavily dependent on Middle Eastern crude. Asian bourses closed mixed, with energy producers there also benefiting from rising commodity prices while broader indices struggled to find footing.
The Strategic Importance of the Strait of Hormuz
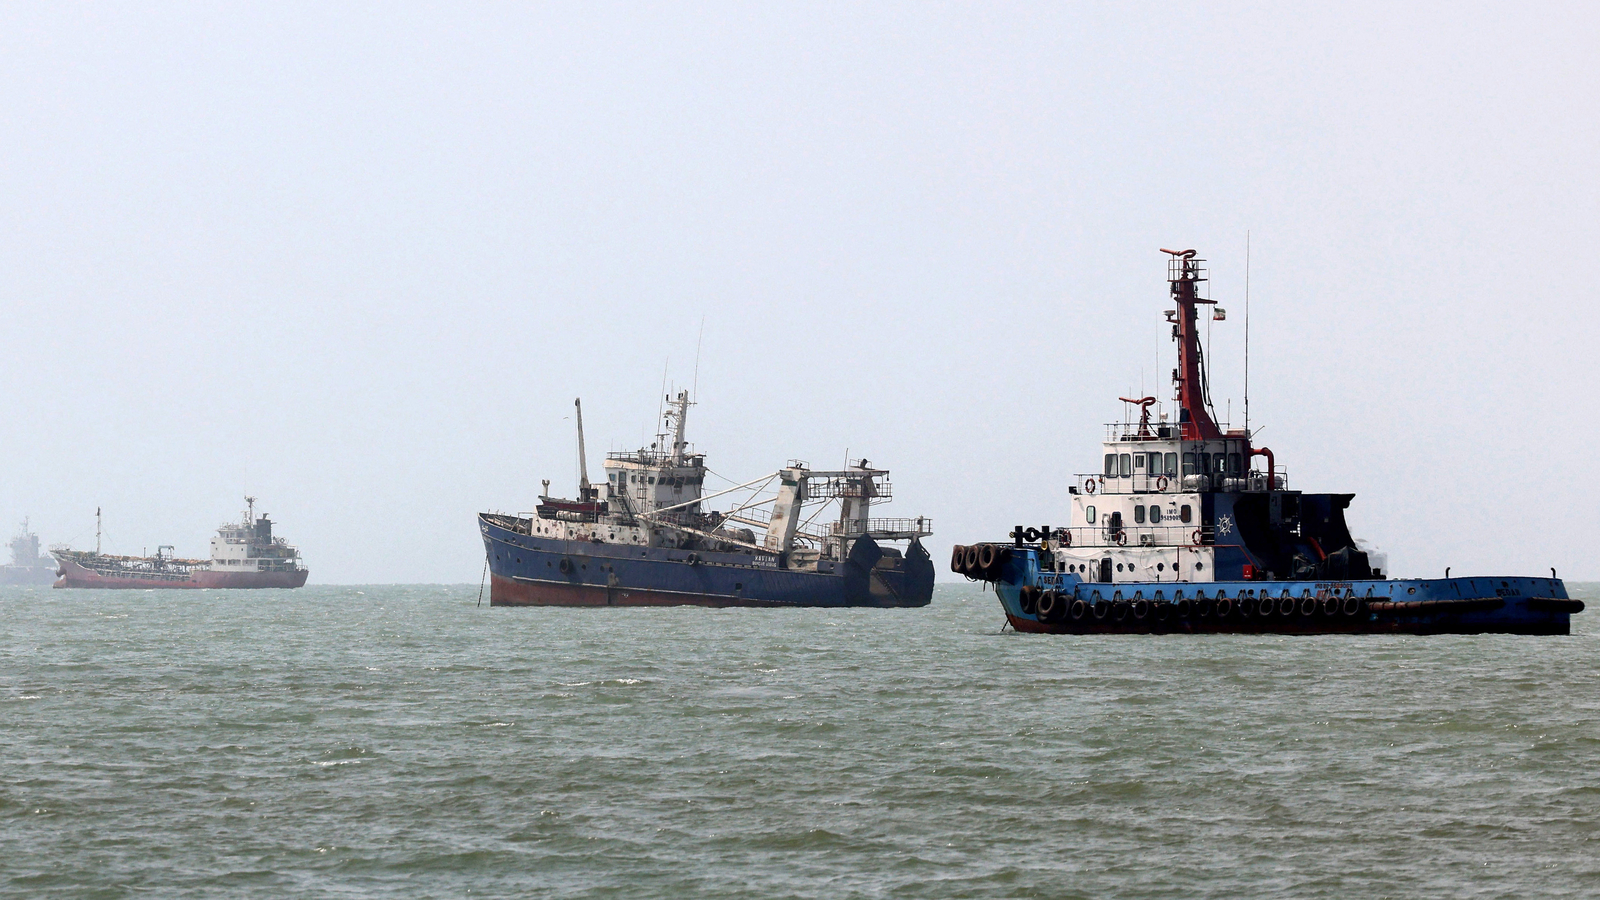
Understanding why a single military strike can move global markets requires understanding just how vital the Strait of Hormuz truly is. This narrow waterway handles approximately 20% of the world’s oil shipments, making it arguably the most important energy transit point on the planet. Any credible threat to its operation sends immediate shockwaves through commodity markets and the broader economy.
The war, now stretching beyond six months, has already curtailed traffic through the strait, and Sunday’s strikes on Iranian rocket launchers only amplified concerns about future disruptions. Compounding the tension, the United Arab Emirates reported intercepting an Iranian drone over its waters on Monday, suggesting the conflict continues to spread geographically beyond its original boundaries.
Brent Crude Leads the Charge Higher
The international benchmark for oil pricing, Brent crude, responded swiftly to the news, climbing 3.2% to settle at $90.91 per barrel. This represents a significant move that brings back memories of the wild price swings seen earlier in the conflict, when Brent traded in a dramatic range between $72 and $102 per barrel as hopes for a diplomatic resolution rose and fell.
The recent oil price surge reflects more than just weekend military activity. Underlying supply concerns, persistent geopolitical risk, and the ongoing war’s cumulative impact on production and shipping logistics have all contributed to keeping prices elevated. Even before Monday’s escalation, oil prices remained stubbornly high compared to pre-war levels, creating a persistent inflationary drag on the broader economy.
Gasoline Prices Hit Painful Records
American consumers are feeling this pressure acutely at the pump. According to AAA data, the national average for gasoline has exceeded $4 per gallon every single day in August, an unprecedented milestone. This August now ranks as the most expensive on record at the fuel station, surpassing even the supply-chain chaos that gripped markets during the COVID-19 pandemic in August 2022.
These elevated fuel costs ripple outward, raising transportation expenses for shipped goods, increasing costs for agricultural products, and squeezing household budgets already strained by years of cumulative inflation.
Inflation Concerns Reshape Fed Expectations
Perhaps no institution watches these developments more carefully than the Federal Reserve, and Monday’s events have complicated its already-difficult position. Inflation continues running well above the Fed’s 2% target, with current rates persistently above 3%. The fresh oil price surge threatens to push these numbers even higher, potentially forcing the central bank to maintain or even increase its hawkish stance.
Wall Street currently anticipates the Fed will raise interest rates at least once more before year’s end, a scenario that would have seemed unlikely just months ago. Treasury yields reflect this shifting sentiment. The two-year Treasury yield, which closely tracks expectations for Fed policy moves, remained at 4.34% as of late Friday, significantly higher than the roughly 3.50% level seen at the start of 2026.
Meanwhile, the 10-year Treasury yield climbed to 4.76% from 4.73% late Friday, returning to levels last seen two weeks ago when the Trump administration took the unusual step of announcing it would intervene directly in the bond market.
The Fed’s Impossible Balancing Act
The Federal Reserve now faces one of the most challenging policy environments in recent memory. Rate hikes designed to tame inflation risk further weakening an already-fragile job market. Rate cuts designed to support employment risk unleashing even more inflationary pressure from energy costs. This is the uncomfortable reality policymakers must navigate as the oil price surge adds yet another layer of complexity to an already-daunting set of decisions.
Labor Market Shows Cracks Beneath the Surface
Speaking of the job market, recent data reveals troubling signs despite what had been a resilient labor environment. The U.S. economy shed 23,000 jobs in July, a surprising reversal from consistent gains. Compounding this concern, Labor Department revisions slashed an additional 103,000 jobs from the previously reported May and June payroll figures, suggesting the slowdown was deeper than initially understood.
This week’s August jobs report will provide crucial insight into whether these weakness signals represent a momentary stumble or the beginning of a more concerning trend. A weaker-than-expected print could pressure the Fed toward more accommodative policy, while a stronger showing might give them room to focus squarely on inflation.
Individual Stock Movers Tell Their Own Stories
Beyond the broader index movements, several individual names made notable moves on Monday. GameStop surged 4.2% after the video game retailer issued a preliminary second-quarter earnings outlook that exceeded its year-ago results, offering a small bright spot for meme-stock enthusiasts and value hunters alike.
Meanwhile, insurance giant Aon dropped 5.8% as the company announced its acquisition of insurance broker USI Insurance Services from private equity firm KKR. The deal, valued at a substantial $17 billion including assumed debt, represents one of the larger insurance industry transactions in recent memory and raised questions about near-term margin pressure and integration challenges.
What Investors Should Watch in the Days Ahead
Several key catalysts could shape market direction in the coming days and weeks:
- August Jobs Report: The most significant data point of the week, with potential to shift Fed expectations dramatically
- Oil Price Trajectory: Whether the oil price surge continues or stabilizes will largely depend on further military developments
- Treasury Market Reactions: Any further government intervention could signal deeper concerns about bond market dysfunction
- Geopolitical Developments: Any diplomatic breakthroughs or further escalations will likely move markets in equal measure
- Corporate Earnings Insights: As more companies report, we’ll get a clearer picture of how higher energy costs are affecting margins across industries
Conclusion: Navigating Unprecedented Uncertainty
Monday’s market action serves as a stark reminder of how interconnected global energy markets, military conflicts, financial systems, and everyday consumer prices truly are. The fresh oil price surge triggered by U.S. strikes on Iranian positions has implications far beyond trading screens, affecting everything from the cost of a gallon of gas to the trajectory of monetary policy to the health of the job market.
For investors, the path forward demands careful attention to a complex web of interrelated factors. Geopolitical developments, Fed communications, employment data, and corporate earnings will all play crucial roles in determining whether the recent market turbulence represents a temporary disruption or the beginning of a more sustained period of volatility.
What remains clear is that the era of predictable, low-volatility markets may be firmly behind us. As long as the Strait of Hormuz remains a contested zone and oil markets remain vulnerable to military action, the kind of sudden, sharp moves seen on Monday will likely become the new normal rather than the exception. Savvy investors will need to stay informed, stay diversified, and stay nimble in the face of an increasingly unpredictable global landscape.