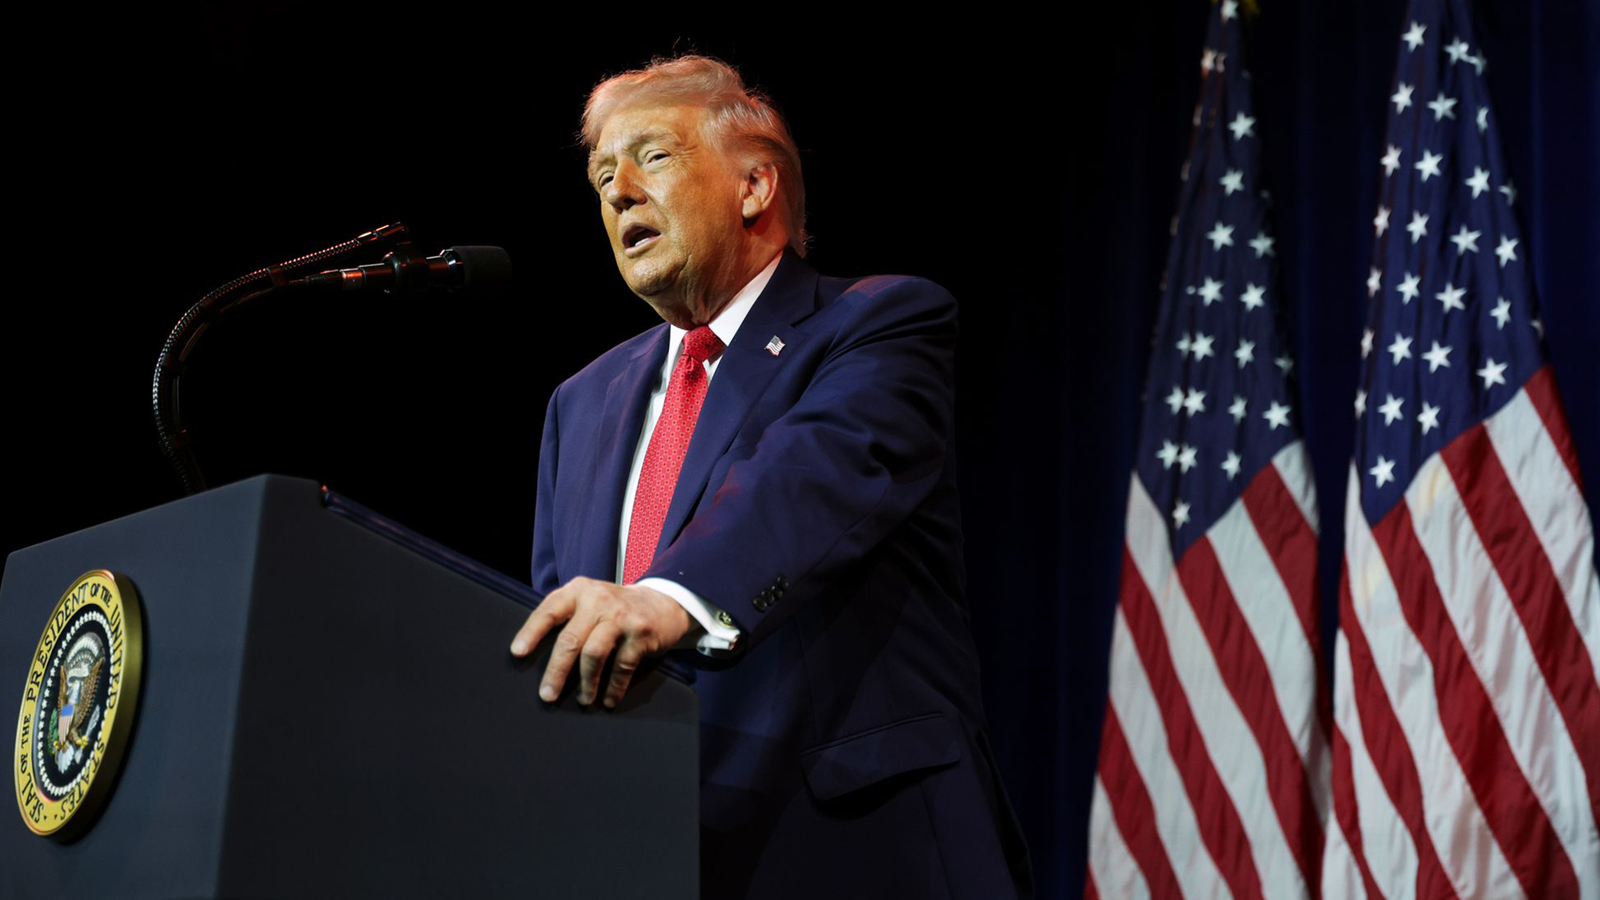
President Trump has announced an aggressive institutional investors housing ban, declaring on social media that he will move immediately to block large corporate entities from purchasing additional single-family homes across the United States. The proposal, which the President says he will also push Congress to codify into law, has already sent shockwaves through Wall Street, with shares of major real estate investment firms tumbling within hours of the announcement. For everyday Americans dreaming of homeownership, the question now becomes: could this policy actually make buying a home more attainable?
The Announcement That Shook Wall Street
In a pointed social media message, the President declared that “people live in homes, not corporations” while outlining his intention to halt the accumulation of single-family residences by deep-pocketed investment firms. The statement was unambiguous in tone and unprecedented in scope, targeting some of the most powerful financial players in the country, including giants like Blackstone, JPMorgan Chase, and other major banks and investment companies.
The market reaction was swift. Blackstone shares dropped by as much as 9% on the day of the announcement, reflecting investor anxiety about what an institutional investors housing ban could mean for the multi-billion dollar single-family rental industry that has flourished over the past decade and a half.
The President has indicated that further details, alongside additional housing affordability proposals, will be unveiled during his upcoming address at the World Economic Forum in Davos later this month.
How Institutional Investors Came to Dominate the Housing Market
To understand why this policy matters, it’s important to recognize just how rapidly institutional investors reshaped America’s residential landscape. According to data from the Government Accountability Office, no investor owned 1,000 or more single-family rental homes as recently as 2011. By 2015, however, institutional investors collectively held approximately 300,000 homes across the country.
The growth accelerated dramatically after the 2008 foreclosure crisis, when Wall Street firms swooped in to acquire distressed properties at bargain prices. Sun Belt cities like Atlanta, Jacksonville, and Charlotte became epicenters of this trend. By 2022, large investors controlled more than 15% of the single-family home market in each of these metros, transforming entire neighborhoods into de facto rental empires.
The Mechanics of Corporate Home Buying
These firms typically purchase homes in bulk, often paying all-cash offers that outbid individual buyers. They then convert the properties into long-term rentals, managing them through professional property management companies. The strategy proved wildly profitable as home prices and rents both climbed in tandem across the post-pandemic era.
The Housing Affordability Crisis Driving the Policy
The push for an institutional investors housing ban didn’t emerge in a vacuum. America’s housing market has reached a breaking point for many would-be buyers. Between the start of 2020 and the third quarter of 2025, home prices surged nearly 55% nationwide, according to a recent report from the National Association of Home Builders.
Several forces converged to create this crisis:
- Historically low inventory: The number of homes available for sale has remained stuck near multi-decade lows, creating intense competition among buyers.
- Elevated mortgage rates: With rates hovering above 6%, monthly payments on a median-priced home have ballooned compared to the pandemic era.
- The rate lock-in effect: Millions of current homeowners secured mortgages at 3% or lower during the pandemic and remain reluctant to sell, knowing they would face significantly higher borrowing costs on their next property.
- Wage stagnation: Income growth has failed to keep pace with the dramatic appreciation in home values.
For first-time buyers and middle-class families, the math simply no longer works in many markets. This frustration has created fertile ground for populist policy proposals aimed squarely at corporate home buyers.
Bipartisan Support for Restricting Corporate Buyers
One notable aspect of the proposed institutional investors housing ban is the political alignment behind the concept. Lawmakers from both parties have introduced legislation in recent years aimed at limiting or banning certain corporate investors from snapping up family homes.
Progressives argue that allowing Wall Street to commodify the American dream is fundamentally wrong, while some conservatives frame the issue as one of free-market fairness, contending that corporations with unlimited capital have an unfair advantage over individual families saving for a down payment.
The Counterargument: Will a Ban Actually Help?
Not everyone is convinced that restricting institutional buyers will solve America’s housing woes. Housing economists and market analysts have raised significant concerns about the potential unintended consequences of such a sweeping policy.
The Rental Supply Question
Perhaps the most pressing concern involves the single-family rental market. Institutional investors don’t just buy homes; they provide rental housing for millions of Americans who cannot afford or don’t want to purchase property. An outright institutional investors housing ban could shrink the supply of purpose-built single-family rentals, potentially driving rents higher in markets where these properties are concentrated.
“This will not fix housing affordability,” noted Jaret Seiberg, an analyst at TD Cowen. “It may boost single-family purchases, but it will come at the cost of reducing single-family rentals.”
The Investment Capital Conundrum
Critics also point out that institutional capital plays a crucial role in new construction and renovation. Blocking these firms from acquiring existing homes could deter investment in housing development at a time when the country desperately needs more supply. If large investors pull back from residential real estate entirely, the ripple effects could touch everything from lumber demand to construction employment.
The Market Share Reality
Even in the most concentrated markets, institutional investors typically control a minority share of single-family homes. While the 15% figure in cities like Atlanta and Charlotte sounds alarming, it still means that roughly 85% of homes in those markets are owned by individuals, small landlords, or other entities. Removing institutional buyers wouldn’t automatically translate into affordable homes for ordinary Americans, particularly when the underlying supply shortage remains unaddressed.
What the Ban Could Mean for Home Buyers
For prospective buyers watching this policy debate unfold, there are several potential scenarios worth considering:
Short-Term Possibilities
- Reduced competition in entry-level markets: If institutional buyers are barred from acquiring more properties, individual buyers may face less cash competition for the limited inventory available.
- Initial price softening: Some markets with heavy institutional concentration could see price adjustments as these firms slow or halt their acquisition strategies.
- Shifts in rental markets: Areas with significant institutional rental presence may see changes in rental availability and pricing.
Longer-Term Considerations
- Policy durability: Without congressional codification, an executive action could be reversed by a future administration, creating uncertainty for the market.
- Legal challenges: Real estate and investment groups are likely to challenge any broad restrictions in court, potentially delaying implementation.
- Market adaptation: Investment firms may find creative workarounds, such as forming partnerships, joint ventures, or new investment vehicles that technically comply with restrictions.
The Broader Housing Policy Conversation
The institutional investors housing ban represents one piece of a much larger puzzle. Even if implemented perfectly, the policy alone cannot resolve the deeply rooted housing affordability crisis facing American families. Meaningful improvement will likely require a multi-pronged approach:
- Increased construction of both single-family and multifamily housing
- Zoning reform to allow more density in supply-constrained urban areas
- Continued investment in affordable housing programs and down payment assistance
- Solutions that address the mortgage rate lock-in phenomenon
The President’s mention of additional “Housing and Affordability proposals” expected during his Davos speech suggests that the institutional investors housing ban may be just the opening salvo in a broader policy rollout.
Conclusion: A Bold Proposal with Uncertain Outcomes
Trump’s proposed institutional investors housing ban represents one of the most aggressive housing policy interventions in recent memory. By directly challenging the role of large investment firms in the single-family home market, the administration is tapping into widespread frustration among American buyers who feel locked out of homeownership by rising prices and limited inventory.
Yet the policy’s ultimate effectiveness remains an open question. While it may create breathing room for individual buyers in heavily institutional markets, experts warn that restricting investment capital could shrink rental supply, deter new construction, and fail to address the fundamental shortage of homes that lies at the heart of America’s affordability crisis. For home buyers, the coming months will be critical. Watch closely for the details of the proposed legislation, the congressional response, and any market signals that indicate whether this ambitious proposal can deliver on its promise of making the American dream of homeownership more attainable for ordinary families.